Thai SMEs buying qualifying software may reduce taxable income by an additional amount equal to the expense. They must check both the supplier and the specific product or service in depa’s catalog before purchasing, commissioning or starting the service. Revenue Department Director-General Notification 469, dated September 30, 2026, sets conditions under Royal Decree 802. The additional relief is capped at THB 300,000 per accounting period. It reduces the tax base; it is not a THB 300,000 cash refund.
Under Royal Decree 802, an eligible purchaser must be a company or juristic partnership with paid-up capital not exceeding THB 5 million at the end of the accounting period, and sales and service revenue not exceeding THB 30 million in that period. The purchaser does not itself need to register with the Digital Economy Promotion Agency (depa), according to the agency’s explanation.
Check the purchase, then separate accounting from tax relief
The legislation covers software, hardware, smart devices and digital services used to manage a business and created or developed in Thailand. Both the supplier and the actual item purchased must be registered before the transaction; a previously registered brand is insufficient. Notification 469 excludes annual maintenance fees and expenses not directly related to the qualifying item.
Software or equipment purchased or commissioned as an asset must be new, meet the depreciation conditions under Section 65 bis (2), and be acquired in a ready-for-use condition by the end of the accounting period in which payment is made. Purchasers must also check the Royal Decree’s restrictions on overlapping relief and use in tax-exempt activities under the laws it specifies.
The following examples are hypothetical. They assume the company, purchase and evidence meet all conditions, including eligibility for SME rates exempting the first THB 300,000 of profit and taxing profit above THB 300,000 up to THB 3 million at 15%. Both start with THB 1 million of taxable profit after ordinary expenses or amortization permitted for tax purposes, but before the special relief. Purchase VAT and withholding tax are omitted.
| Example | A: Software service | B: New software asset |
|---|---|---|
| Actual qualifying expenditure | THB 10,000 monthly throughout the year: THB 120,000 | Purchased, paid and ready for use on January 1, 2026: THB 240,000 |
| Accounting entry | Each month: debit service expense THB 10,000; credit bank THB 10,000 | Debit software asset THB 240,000; credit bank THB 240,000, then recognize amortization under the applicable rules |
| Additional reduction to taxable income | THB 120,000 | THB 240,000 in the payment period, if all conditions are met |
| Taxable income after special relief | THB 880,000 | THB 760,000 |
| Tax before credits: without → with relief | THB 105,000 → THB 87,000 | THB 105,000 → THB 69,000 |
| Hypothetical tax saving | THB 18,000 | THB 36,000 |
For example B, assuming a three-year accounting useful life, straight-line amortization, no residual value and availability from the first day of the period, first-year amortization is THB 80,000. The entry debits amortization expense and credits accumulated amortization. Three years is an assumption, not a mandatory life for every business. The company must consider its applicable accounting standard and tax treatment under Section 65 bis (2) separately.
The additional relief belongs in the tax calculation, without recording the expense or asset again. If qualifying expenditure totals THB 420,000, additional relief remains capped at THB 300,000 per period. The table’s THB 105,000 / 87,000 / 69,000 amounts are before tax credits, such as P.N.D.51 payments and withholding tax, and do not necessarily equal the extra payment due on filing. Revenue Department rates and tax calculation.
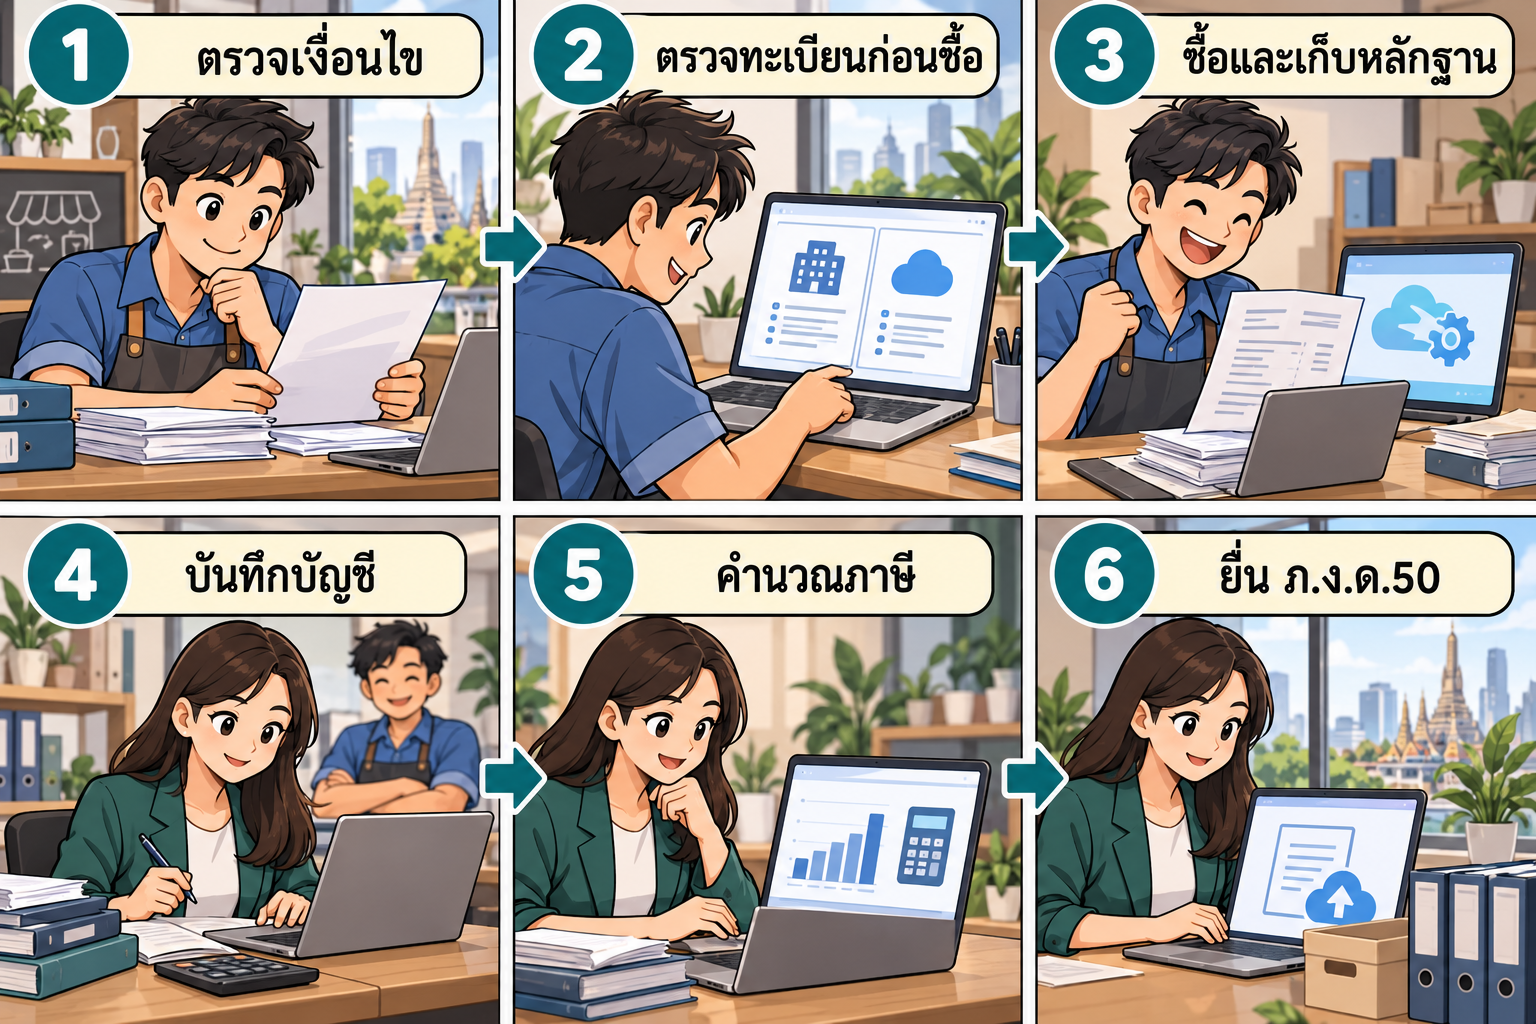
AI-generated explanatory illustration with Thai labels. Its six steps are: check eligibility; verify registration before buying; buy and retain evidence; record the accounting entries; calculate tax; and file P.N.D.50. It does not certify tax eligibility; screens and documents shown are fictional.
Filing dates and two points requiring clarification
The Royal Decree’s expenditure window is June 24, 2025–December 31, 2027. Notification 469 additionally refers to expenditure paid in an accounting period starting on or after June 24, 2025. A business whose period began earlier but paid later should confirm eligibility with the Revenue Department rather than assume it qualifies.
The second issue concerns computers. The Royal Decree excludes computers, while Notification 469 refers to computers not approved for registration. The general explanation therefore treats computers as excluded. If a registered model is found, ask the Revenue Department about the difference in wording before claiming relief.
| Timing: example period January 1–December 31, 2026 | Required action |
|---|---|
| Before purchase and during the year | Check registration before the transaction; retain tax invoices, contracts, payment and use evidence |
| By period-end and after closing the accounts | Purchased or commissioned assets must be ready for use by period-end. Prepare a report stating the item/service type, use and ready-for-use date; retain it with evidence at the business premises |
| Within 150 days after period-end | File P.N.D.50 with the relevant relief attachment. Day 150 is May 30, 2027, a Sunday, so Monday May 31, 2027 is expected if there is no additional holiday. Confirm the actual calendar before filing |
The 150-day rule comes from the Revenue Department, with the next-working-day treatment in Order P.117/2545. The online-filing extension notice currently verified covers statutory deadlines only through January 31, 2027. An extra eight days has therefore not been added to this May 2027 example; check for a new notice closer to filing.
Businesses budgeting for a new system should have their accounting team check registration, contract line items and the payment period before purchasing. This article explains the rules and hypothetical examples as of October 11, 2026; it does not certify eligibility for any company or product.